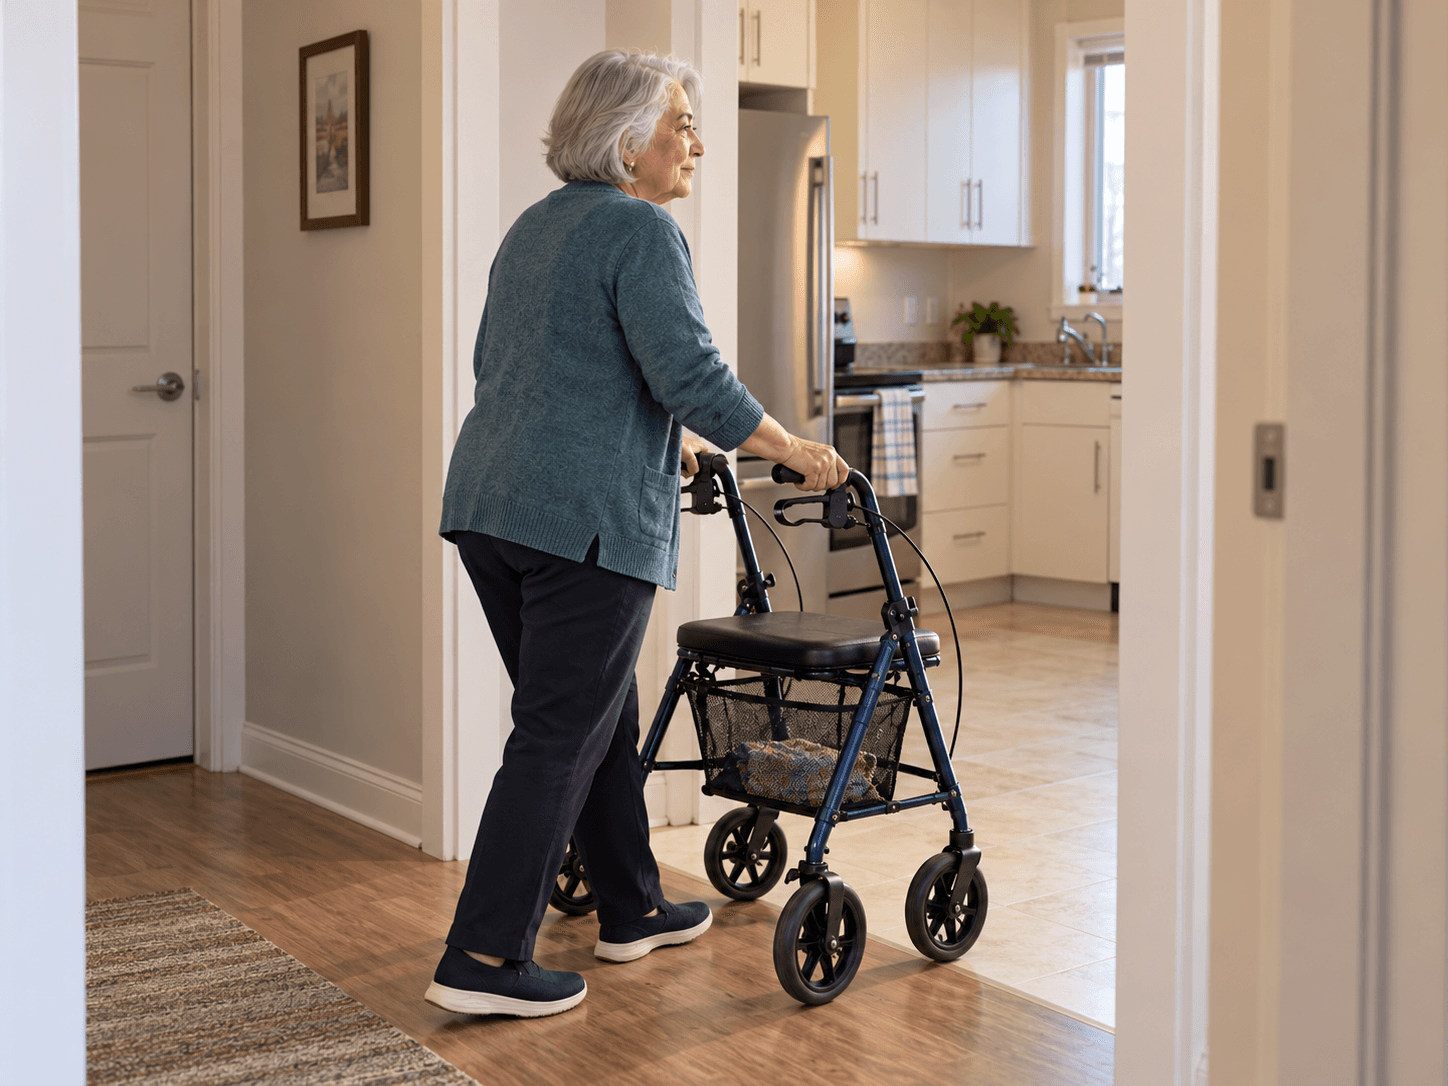
Hélène, 76, buys a walker for use in her Gatineau apartment. She puts the receipt beside a bathroom renovation estimate, then wonders whether both belong under the same credit. The purchase needs a closer look than the word "accessibility" on a sales brochure.
Quebec's refundable independent living credit covers specified equipment and fixtures, as well as certain rehabilitation stays. It is not a general credit for every renovation that makes a home more comfortable.
Match the purchase to the eligible list
For a 2025 claim, you must have been at least 70 and resident in Quebec on December 31. You or your spouse must have paid the qualifying expenses. Eligibility overview.
The equipment must be for your principal residence. Examples on the list include walkers, hearing aids, non-motorized wheelchairs, specified monitoring devices and certain bathing or toilet aids. Purchase, lease and installation costs can qualify. Match the actual item to the official list before treating a broad contractor invoice as eligible. Equipment and claim rules.
Hélène keeps the model description with the receipt. If her bathroom project proceeds, she asks for separate descriptions and prices for the relevant fixture, installation and other work. "Bathroom renovation" alone does not explain what was purchased.
Subtract the first $250 before applying 20%
For the equipment portion, the first $250 of eligible expenses is excluded. The credit rate is 20%. Suppose Hélène has $750 of qualifying costs, with no reimbursement and no conflicting credit claim:
- Eligible equipment costs: $750.
- Less the excluded portion: $250.
- Amount used in the calculation: $500.
- Credit: $500 × 20% = $100.
The $250 is subtracted from the eligible total; it is not a $250 credit. Complete Part E of Schedule B for the claim reported at line 462.
Check reimbursements and other claims first
The instructions exclude reimbursed or reimbursable costs, subject to a specified taxable-reimbursement exception. They also exclude expenses used to calculate another refundable or non-refundable credit, including medical expenses or home-support services. Compare the applicable claims before assigning the receipt.
Write the amount actually borne, any insurance reimbursement and the chosen claim beside your saved calculation. That makes it easier to check a later reimbursement or explain why the receipt was not included in another total.
The credit also covers qualifying stays in a functional rehabilitation transition unit, with separate rules including a 60-day limit per stay. An ordinary convalescence bill is not automatically such a stay. Those costs should be reviewed separately from the equipment calculation.
For paid cleaning, snow removal or other ongoing assistance, see the home-support services guide. Hélène's walker purchase and a cleaner's invoice answer different questions on the return.
Checked October 20, 2026, against the 2025 return instructions.