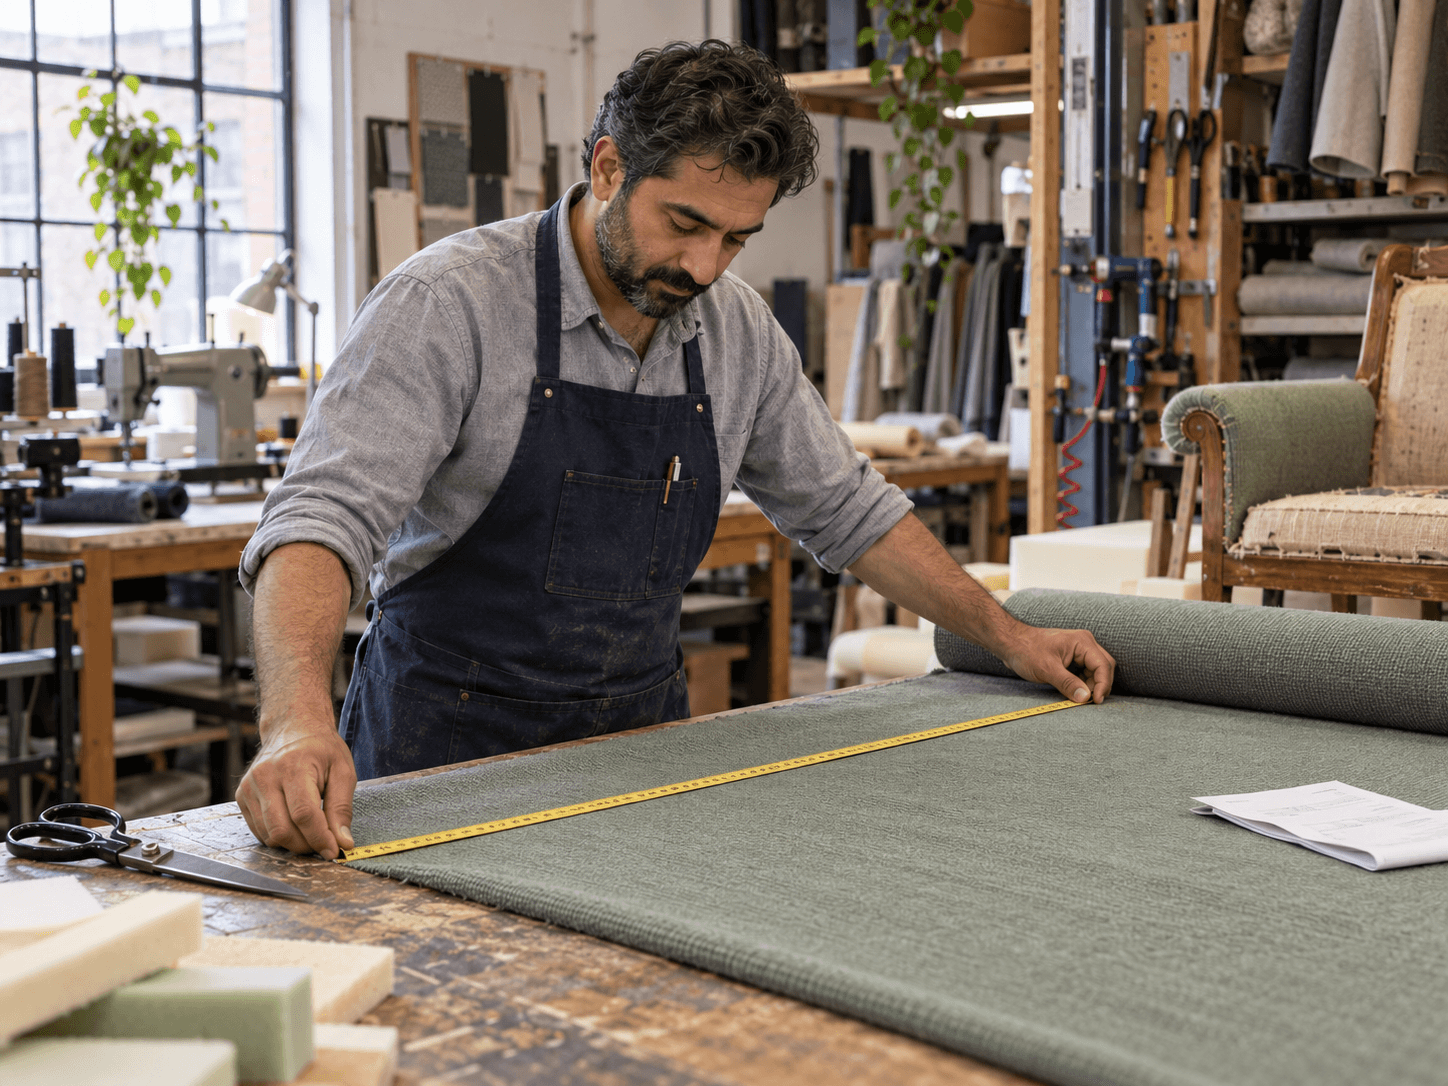
The fabric arrives before the chair is ready. Nabil checks the colour, the length and the supplier's invoice. For his Montreal upholstery business, the purchase record has two tax amounts to review.
An input tax credit (ITC) recovers eligible GST/HST; an input tax refund (ITR) recovers eligible QST. Registration, the purchase and its use all matter. The tax must be paid or payable, and personal purchases or costs of exempt activities generally do not qualify. Revenu Québec's eligibility overview.
Keep the purchase cost and each tax separate
Assume Nabil is registered for both taxes, uses the regular method and buys $200 of ordinary supplies solely for taxable upholstery work. The invoice shows:
| Record | Amount |
|---|---|
| Supplies before tax | $200.00 |
| GST, potentially an ITC | $10.00 |
| QST, potentially an ITR | $19.95 |
| Invoice total | $229.95 |
Once the conditions and documents are checked, the recoverable taxes are $10 and $19.95. The $200 purchase price is not another sales-tax credit. Claiming these amounts also does not necessarily produce a cash refund: they enter the net-tax calculation alongside tax on sales.
For ordinary operating expenses with mixed use, the commercial share matters. A reasonable 60% commercial allocation generally supports 60% of the eligible tax. Keep the calculation and use a consistent allocation method. Equipment, vehicles and other capital property can have different rules; do not apply the operating-expense percentage to every asset. Operating-expense rules.
Read the supplier's QST number
A digital service can create a different problem. Some suppliers outside Quebec and platform operators use the specified QST system, with NR in their registration number. QST paid to such a supplier does not qualify for an ITR, even on a business purchase.
A business registered under the general QST system should provide its number containing TQ before the transaction so the supplier does not charge QST. If it was already charged, request the refund directly from the supplier. Adding it to the ordinary ITR total is not the correction. The NR supplier exception.
Match the claim to its document and period
Check the supplier, date, description, tax amounts and required registration information against the invoice documentation rules. If information is missing, ask for it before relying on the claim. Nabil's worksheet also records the eligible share, reporting period and whether the amount has already been claimed.
Most claims go on the return for the relevant purchase period. A four-year claim window generally applies, with shorter periods for some registrants. Use the deadline tied to the applicable reporting period, not a guessed anniversary of the payment. Quick Method users generally cannot claim these taxes on most operating purchases, and pre-registration purchases need separate rules. Claiming ITCs and ITRs.
Save readable records, including digital invoices. They generally need to remain available for six years after the end of the last year to which they relate, and longer where an objection or court challenge requires it. Record retention.
Nabil's final check is simple: each claimed tax amount leads back to an eligible purchase, a usable document and the correct return. The fabric can then become a chair instead of another unidentified line in his bookkeeping.
Checked October 20, 2026. This example uses the regular method for an ordinary registered commercial business.