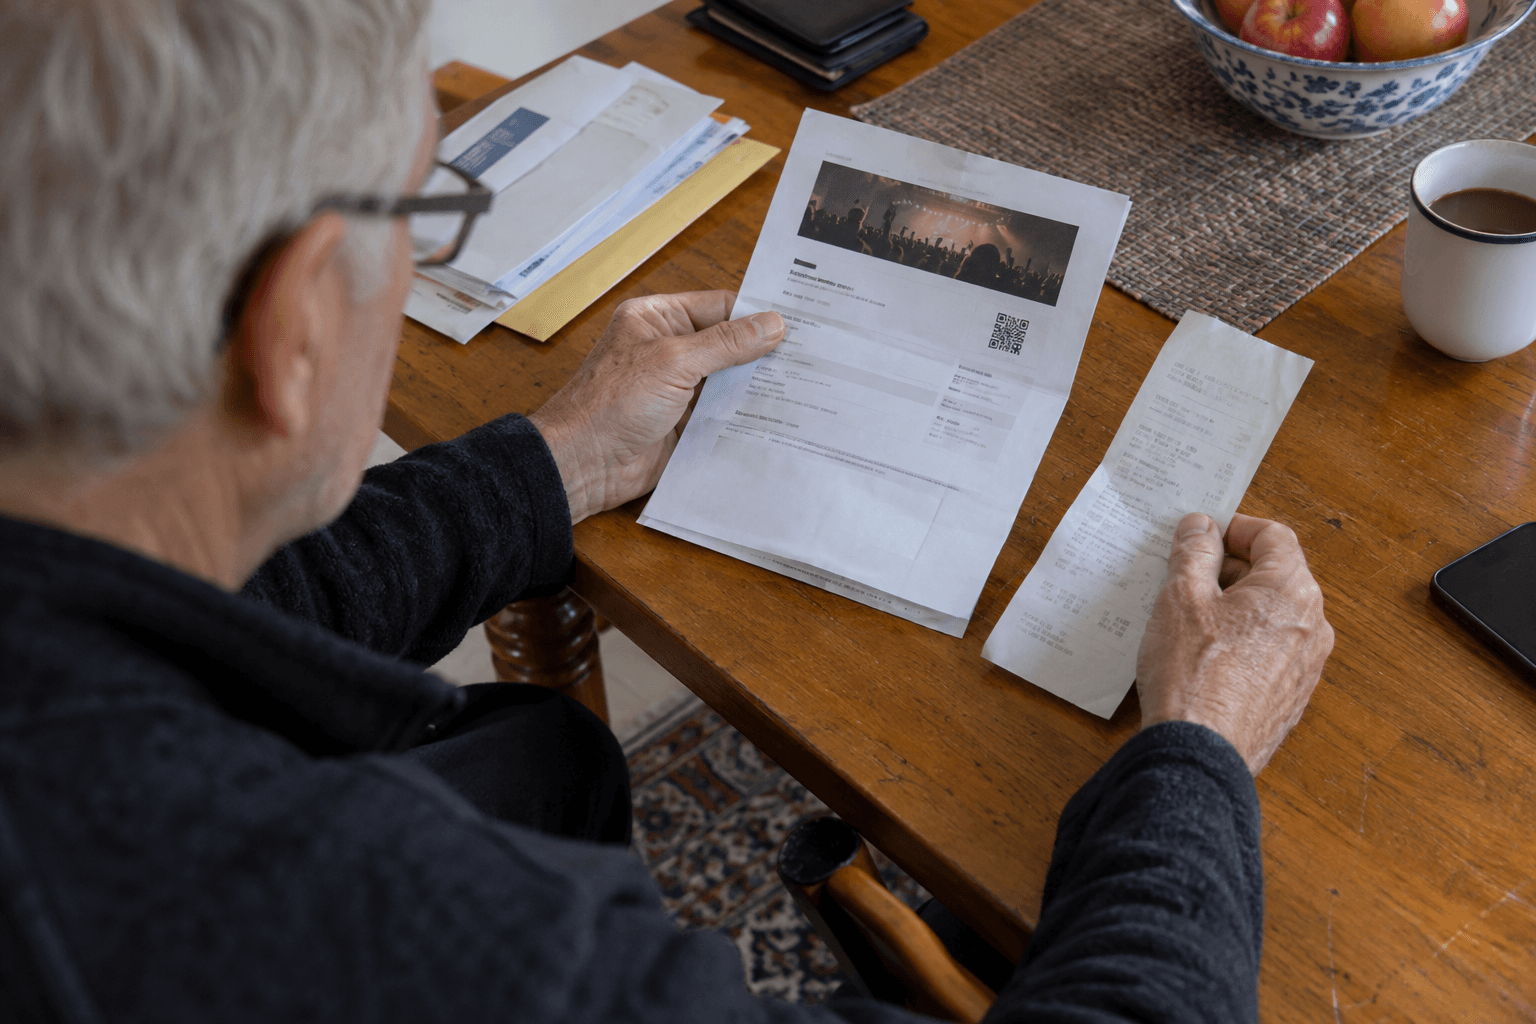
Étienne buys a ticket to a community fundraiser and receives a friendly confirmation email. In his tax folder, he places it beside a registered charity's official donation receipt. They look equally convincing, but serve different purposes.
A purchase confirmation or thank-you message does not necessarily support a charitable donation credit.
Find the official eligible amount
A claim generally requires an official donation receipt from a qualified donee. Check the organization's status and the receipt's details rather than relying on its name or the cause it supports.
Where the donor receives a benefit, the eligible gift amount can be less than the payment. If a $120 event payment produces an official eligible amount of $70 after the relevant benefit, Étienne uses the receipt's eligible amount, not the card charge. He does not invent that allocation himself.
Ordinary purchases, volunteer time and money given directly to an individual do not automatically qualify as charitable donations. A platform's payment record should be matched to the actual official receipt where one is issued.
Check whose return will use it
A couple can review eligible donations together under the applicable spousal rules. The same receipt cannot be claimed twice. Étienne keeps a simple register with the donation date, eligible amount, person claiming it and tax year used.
For ordinary eligible gifts, unused amounts can generally be carried forward for up to five years. Older carried-forward amounts are used first. Special gifts and circumstances can have different rules.
Keep a claim history
A receipt saved again in next year's folder is still the same donation. Mark the amount already claimed and the balance carried forward rather than relying on memory.
The credit reduces tax under its calculation; it does not refund the full gift dollar for dollar. Étienne retains the official receipt and his allocation record so the return reflects both the donation and its actual tax treatment.